

Top Software Companies in Toronto (836)

Rokt is the global leader in ecommerce, unlocking real-time relevance in the moment that matters most - The Transaction Moment. Rokt’s AI Brain and Ecommerce Network powers billions of transactions connecting hundreds of millions of customers, and is trusted to do this by the world’s leading companies including Live Nation, Macy’s, Fanatics, AMC Theatres, PayPal, Uber, Hulu, Staples, Albertsons and...
Rokt's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is described at roughly $600M in 2024 with about 43% year-over-year growth and an estimated $900M annualized run-rate by October 2025. External recognitions like Deloitte Technology Fast 500 and the FT Americas’ Fastest Growing Companies 2026 align with this expansion trajectory.
Product Line Growth: Acquisitions of AfterSell (2024), mParticle (January 2025), and Canal (July 2025) expanded capabilities into SMB upsells, customer data platform functionality, and distributed commerce via Rokt Catalog. These additions broaden the offering beyond core checkout ads and support continued scale.
Investor Backing & Capital Strength: A January 16, 2025 secondary share sale valued the company at about $3.5B, signaling strong late-stage investor support. Coverage also notes a potential 2026 IPO target, consistent with capital-markets readiness.
At Capital One, we think and work like a tech company, using our digital fluency to transform everything about the customer experience. We’re bending data to our will, and turning a stodgy industry on its head. That’s reflected in our ranking as the number one business technology innovator in the U.S. in the 2016 InformationWeek Elite 100.
Capital One's Top Stability & Growth Strengths
Strong Revenue Growth: Q2 2026 total net revenue rose 4% sequentially to $15.9 billion. Integration of Discover and Brex contributed to higher non‑interest income and broader payments capabilities.
Profitability: Q2 2026 net income reached $3.0 billion, up from $2.2 billion in Q1 2026, alongside a net interest margin of 8.01%. Management also cited strong credit performance, including a $662 million reserve release.
Market Expansion: Acquisition‑driven scale is broadening reach, with the Discover deal (closed May 18, 2025) and Brex (closed April 7, 2026) adding network and corporate card/spend‑management capabilities. Balance‑sheet growth continued in Q2 2026 as period‑end loans rose 2% to $457.2 billion and total assets reached $673.8 billion.
KUBRA provides customer experience management solutions to some of the largest utility and government entities across North America. Our portfolio includes billing and payments, alerts and preference management, artificial intelligence solutions, mobile apps, and utility mapping solutions. KUBRA reaches over 40% of households in the U.S. and Canada, providing performance-driven value to more than 475 clients and their customers.
KUBRA's Top Stability & Growth Strengths
Strong Market Position & Advantage: KUBRA is described as reaching over 40% of U.S. and Canadian households and serving 250–475+ enterprise clients, placing it in the top competitive set for utility/government bill presentment and payments. This visible scale and recognition, reinforced by REPAY’s acquisition framing, indicate an entrenched position in resilient, recurring‑billing verticals.
Product Line Growth: Recent launches such as KUBRA HQ (October 2025) and the EZ‑PAY+ expansion (February 2026) show continued investment in billing, payments, and communications capabilities. These additions broaden use cases and support cross‑sell and upsell potential within existing accounts.
Investor Backing & Capital Strength: REPAY closed the acquisition on June 1, 2026 and guided $150–$154 million of KUBRA revenue contribution for the remaining seven months of 2026 with a multi‑year synergy roadmap. The combination implies added investment capacity and cross‑sell leverage across a platform processing roughly $130 billion in annual payment volume.
Block, Inc. is a global technology company with a focus on financial services. Made up of Square, Cash App, Afterpay, TIDAL, Bitkey, and Proto, Block, Inc. builds technology to increase access to the global economy. Each of our brands unlocks different aspects of the economy for more people. Square makes commerce and financial services accessible to sellers. Cash App is the...
Block's Top Stability & Growth Strengths
Profitability: Record adjusted operating income and margin accompanied the growth, with management lifting 2026 adjusted operating income guidance to a higher margin level. Operating leverage was emphasized alongside strong second‑quarter results.
Resilient & Sustainable Growth: Gross profit accelerated year over year into Q2 2026 (after an even stronger Q1), and full‑year 2026 gross profit guidance was raised meaningfully. Leadership framed gross profit as the clearer indicator of underlying momentum given revenue mix effects.
Cost & Operational Efficiency: Efficiency measures, including running a leaner organization, boosted margins and contributed to record profitability. Leaders also pointed to continued strength into the second half with healthy monetization and risk metrics, indicating efficient scaling.

At General Motors, our vision is to create a world with Zero Crashes, Zero Emissions, and Zero Congestion. We wholeheartedly embrace the responsibility to lead the change that will make our world better, safer, and more equitable for all. Our industry and company are undergoing a once-in-a-lifetime technological transformation, which is reshaping our approach to technology and innovation. We are expanding...
General Motors's Top Stability & Growth Strengths
Profitability: Profit metrics and margins are rising in 2026, with Q2 EBIT‑adjusted up ~30% to $3.94B and the margin improving to 8.2%, alongside a first‑half margin of 8.9%. Management also raised full‑year 2026 profit guidance to $14–$16B, reflecting stronger earnings power driven by mix, pricing, and cost discipline.
Healthy Cash Flow: Adjusted automotive free cash flow grew sharply (up 78% in Q2 and 73% year to date), and the company reinforced confidence by declaring a $0.18 quarterly dividend and authorizing a $6B buyback. These capital returns accompany higher full‑year free‑cash‑flow guidance of $9.5–$11.5B.
Diversified Revenue Streams: Software‑enabled services and subscriptions are contributing more meaningfully, with roughly 620,000 subscribers, $5.4B of deferred revenue at 2025 year‑end, and OnStar revenue up ~20% year over year in Q2 2026. The company indicates software revenue is on track to exceed $3B in 2026.
.png)
Applied is the connective intelligence transforming how insurance works. We build the platforms, data, and agentic systems that connect the entire insurance journey, turning months of manual work into moments. We keep work flowing, from thousands of agencies and carriers to the millions of policyholders they protect.
Applied Systems's Top Stability & Growth Strengths
Strong Revenue Growth: S&P Global Ratings described multi‑year revenue growth with continued expansion expected, and inclusion on the 2026 Inc. 5000 points to sustained momentum. Company materials also cite a long‑run growth rate and record trading and adoption metrics in 2024–2025.
Innovation-Driven Growth: New AI‑driven capabilities in 2026 and the acquisitions of Planck (2024) and Cytora (2025) expand automation across intake, underwriting, reconciliation, and quoting. Ongoing enhancements across Epic and EZLynx and initiatives like an agentic email‑to‑quote channel indicate active product investment and monetization.
Strong Market Position & Advantage: Adoption signals include standardization by many top brokers, record attendance at Applied Net 2025, and recognition on G2 in 2026. Customer case examples and ecosystem reach reinforce a durable position in the independent‑agency software market.
.png)
Arrive Logistics is a top 4 American truckload brokerage headquartered in Austin, Texas, with 10 locations across North America. Founded in 2014, Arrive delivers unparalleled service and custom strategic solutions to a diverse network of globally recognized brands and vetted carriers. Arrive has 2,000 employees, 5,500 customers, and 10,000 core carriers in its network. The Company has been recognized for...

Arrive Logistics's Top Stability & Growth Strengths
Strong Revenue Growth: Company posts indicate it finished 2025 at about $2.7B in revenue with a Q4 run-rate near $3B, alongside >25% truckload volume growth. Earlier disclosures show a climb from ~$0.8B in 2020 to the billions by 2025, reflecting a sustained top-line expansion.
Profitability: Leadership highlights positive net income in 2025 and notes the business ended 2024 profitably. Growth investments in technology and expansion are being pursued alongside earnings, underscoring disciplined scaling.
Cost & Operational Efficiency: Internal cost per load fell and management reports productivity gains tied to its technology platform, with further improvements targeted in 2025. These efficiency trends are presented as levers to manage volatility while scaling.
.png)
Since we opened our doors in 2009, the world of commerce has evolved immensely, and so has Square. After enabling anyone to take payments and never miss a sale, we saw sellers stymied by disparate, outmoded products and tools that wouldn’t work together. So we expanded into software and started building integrated, omnichannel solutions – to help sellers sell online, manage...

Square's Top Stability & Growth Strengths
Resilient & Sustainable Growth: Square gross profit and payment volumes are rising with signs of acceleration in 2026; Q2 2026 gross profit reached about $1.16B and GPV increased at a low‑teens rate year over year. Management also raised the full‑year outlook at the Block level, indicating momentum in which Square is contributing.
Market Expansion: Traction with larger, multi‑location sellers and strong international GPV growth indicate expansion beyond very small businesses. U.S. GPV also accelerated to its strongest pace since Q2 2023, complementing faster non‑U.S. growth.
Innovation-Driven Growth: Hardware and AI are highlighted as fast‑compounding capabilities, and Square Financial Services has begun processing acquiring volume. An expanded ISO and partner ecosystem is bringing in more new sellers and deepening product adoption.
 copy.jpg)
At 8am, our vision is to power a world where professionals thrive. We start every day on a mission to empower professionals with the most trusted, innovative technology to deliver world-class outcomes for their clients and exceptional financial results for their business. They count on our purpose-built solutions to simplify operations, ensure compliance, and fuel profitable growth, so they can...

8am (Formerly AffiniPay)'s Top Stability & Growth Strengths
Strong Revenue Growth: Company communications highlight multi‑year revenue acceleration around the 2025 rebrand, alongside rising ARR and payment volume into 2026. Repeated Inc. 5000 recognition underscores sustained top‑line expansion.
Investor Backing & Capital Strength: A significant 2024 investment by Genstar Capital alongside TA Associates is positioned to fuel the next phase of scale. The 2026 appointment of a growth‑oriented CEO signals capacity to deploy this capital toward expansion.
Product Line Growth: LawPay was expanded into a broader financial management suite with offerings such as Smart Spend and a Visa business card, while multiple brands were unified under one platform to enable cross‑sell. New AI capabilities and integrations further extend the portfolio’s surface area.

Citadel Securities is a technology-driven, next-generation global market maker. We provide institutional and retail investors with world-class liquidity, competitive pricing and seamless front-to-back execution in a broad array of financial products. Our teams of engineers, traders and researchers harness leading-edge quantitative research and the accelerating power of compute, machine learning and AI to power our analytics and tackle the market’s...
Citadel Securities's Top Stability & Growth Strengths
Strong Revenue Growth: Recent disclosures point to record annual and early‑year trading results in 2025–2026, signaling sustained top‑line momentum. Company communications also highlight elevated platform activity in options and expanded client analytics, reinforcing growth.
Market Expansion: A new Amsterdam office and recent build‑outs in Tokyo and Sydney indicate active geographic scaling across Europe and Asia‑Pacific. Increased global hiring across trading, engineering, and research supports deeper regional coverage and client reach.
Strong Market Position & Advantage: Materials emphasize a leading role in U.S. equities and retail order flow alongside prominent standings in U.S. Treasuries and investment‑grade credit. Record retail options activity and investment in high‑touch coverage integrated with electronic scale suggest durable competitive advantages.
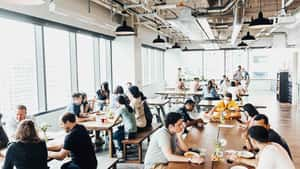
Qualtrics is trusted by thousands of the world’s best organizations to power exceptional customer and employee experiences that build deep human connections, increase customer loyalty, boost employee engagement, and drive business success. Our advanced AI and specialized Experience Agents™ allow businesses and governments to proactively interact with customers and employees in personalized ways across every channel and touchpoint, respond in-the-moment...
Qualtrics's Top Stability & Growth Strengths
Strong Market Position & Advantage: Independent analysts continue to place Qualtrics at the front of its market, with Gartner naming it a Leader in the Magic Quadrant for Voice of the Customer Platforms and positioning it highest on Ability to Execute and furthest on Completeness of Vision. This standing typically aligns with robust enterprise demand and supports commercial momentum.
Market Expansion: The company closed a $6.75 billion acquisition of Press Ganey Forsta on May 18, 2026, materially expanding its healthcare experience footprint and enlarging its data assets. Such scope increases are noted as common precursors to revenue growth and broader vertical penetration.
Innovation-Driven Growth: Qualtrics highlights rapidly expanding AI capabilities and analysis of billions of interactions annually, with usage of AI features surging and adoption widespread among large enterprise accounts. This product momentum supports upsell and cross‑sell into the installed base.
Together, we've turn ambition into action. For more than three decades, Citadel has captured undiscovered market opportunities in markets around the world by empowering extraordinary people to pursue their best and boldest ideas. We strive to identify the highest and best uses of capital to generate superior long-term returns for the world’s preeminent public and private institutions.
Citadel's Top Stability & Growth Strengths
Profitability: All‑time profit leadership and continued gains in 2024–2025 underpin sustained investor demand and fee generation. Returning roughly $5 billion of 2025 profits while maintaining about $66–$67 billion in AUM highlights durable earnings and disciplined sizing.
Market Expansion: The Miami headquarters build, additional 2026 real‑estate purchases, and a planned Dubai office point to an expanding physical footprint and long‑dated strategic commitments. Acquisitions in power and energy trading (e.g., FlexPower and Paloma Natural Gas) extend reach into global commodities markets.
Strong Hiring & Retention: Ongoing large‑scale recruiting, including new cohorts for the Citadel Associate Program and other early‑career pipelines, signals sustained investment in talent to support platform growth.
Supernova is the technology leader in securities-based lending ("SBL") solutions that connect and empower the entire financial ecosystem. We offer the world’s first and only cloud-based, fully-customizable, end-to-end software solution to automate securities-based lending from origination through the life of the loan.

Supernova Technology's Top Stability & Growth Strengths
Market Expansion: The company announced an expansion into the UK in early 2026, naming local leadership to drive partnerships and growth in Lombard lending. This extends its footprint beyond the U.S. into a key wealth market and broadens distribution.
Product Line Growth: In 2024 it launched Prism, an AI‑powered document assistant, and a next‑generation cloud collateral‑management solution supporting multiple asset types. These releases expand capabilities beyond core SBL workflows into adjacent operational functions for banks and wealth platforms.
Strategic Partnerships: Relationships include a 2024 collaboration with R&T Deposit Solutions and a Supernova‑powered rollout at Old National Bancorp in late 2023, alongside earlier work with AssetMark Trust. These partnerships signal growing institutional adoption and added go‑to‑market channels.
BuildOps is the AI-native platform for commercial contractors. Built for the complexity of large-scale commercial work, it replaces disconnected tools and manual workflows with a single system that runs every job from quote to close. At the center of the platform is OpsAI, BuildOps' intelligence layer designed for real work in the trades. OpsAI helps dispatchers send the right tech in...
BuildOps's Top Stability & Growth Strengths
Investor Backing & Capital Strength: BuildOps closed a $127M Series C in March 2025 at a $1B post‑money valuation, providing substantial capital to scale. Participation by top‑tier investors and the valuation step‑up indicate strong external confidence.
Strong Revenue Growth: Leadership stated revenue doubled in 2023 and 2024, and the company later appeared on the 2026 Inc. 5000 list, both pointing to sustained multi‑year expansion. Rising customer totals from 1,000+ to 1,500+ align with that trajectory.
Market Expansion: The company established a major hub in Raleigh and opened a dedicated Canadian HQ in Toronto in 2026, extending its geographic footprint. Reported headcount increases at these sites are consistent with scaling operations.
Initially built to take the pain out of peer-to-peer payments, Cash App has gone from a simple product with a single purpose to a dynamic app, bringing a better way to send, spend, invest, borrow and save to our millions of monthly active users. With a mission to redefine the world's relationship with money by making it more relatable, instantly...

Cash App's Top Stability & Growth Strengths
Profitability: Gross profit is rising rapidly, with Cash App up 31% year over year in Q2 2026 and companywide gross profit also expanding. Guidance was raised on the strength of Cash App and Square, underscoring ongoing profit momentum.
Cost & Operational Efficiency: Management is prioritizing gross profit per employee and operating margins, aiming to run a smaller company while continuing product and user growth. The February 2026 restructuring was framed around “disciplined growth” and AI‑driven efficiency.
Resilient & Sustainable Growth: Users and engagement are trending up, with about 59 million monthly actives at end‑2025 and accelerating inflows per active alongside rising “primary banking” usage. Momentum carried into 2026, with strong early‑year gross profit growth supporting raised full‑year outlook.
As the AI platform for business transformation, we're putting AI to work across organizations — freeing people for work that matters. Making old tech work with new tech. Reaching across departments, from the front office to the back office and every office in between. Our ambition? To become the AI defining enterprise software company of the 21st century (or "AI...
ServiceNow's Top Stability & Growth Strengths
Strong Revenue Growth: Subscription revenue reached $3.877B in Q2 2026, growing strongly year over year, with total revenue also advancing. The company raised its full-year 2026 subscription outlook to $15.76–$15.78B and guided continued double-digit growth into Q3.
Product Line Growth: “ServiceNow AI” surpassed $1B in ACV in Q2 2026, acting as a catalyst for deal activity and upsell. Newer AI capabilities layered onto core workflows are described as adding incremental momentum.
Resilient & Sustainable Growth: Current and total RPO climbed to $13.20B and $29.0B, respectively, indicating strong contracted demand ahead. The number of customers above $5M in ACV increased meaningfully, supporting durable multi‑year expansion.
Performance-driven learning & development teams achieve business impact with 360Learning. L&D teams leverage AI and collaborative learning to pinpoint skills gaps, capture knowledge from experts, and deliver it to learners when needed most. 360Learning’s learning platform is equipped with powerful LMS automation, collaborative learning Academies, tools to create a top-notch learner experience, and an AI-powered Skills ontology to activate skills-based...

360Learning's Top Stability & Growth Strengths
Strong Revenue Growth: Estimated 2024 revenue or ARR around ~$60M and messaging of 2,500+ customers point to continued scaling. North America has been a growth engine with reported ~65% average year‑over‑year growth and more than 15% of revenue.
Investor Backing & Capital Strength: A $200M round in October 2021 led by Sumeru, SoftBank Vision Fund 2, and Silver Lake Waterman—bringing total funding to roughly $240M—provides capacity for product investment, hiring, and M&A. A 2025 grant adds incremental support for AI and skills initiatives.
Strategic Partnerships: A partnership with Workday announced on Nov 13, 2025, and integrations with major HCM platforms like UKG expand enterprise routes to market. These alliances can enhance distribution in mid‑market and enterprise segments.
.png)
Expedia Group, Inc. is the global travel marketplace with one purpose: to help travelers explore the world, one journey at a time. Expedia Group™ connects travelers, partners, and advertisers through its trusted brands, leading technology, and rich first-party data, delivering predictive, personalized experiences that shape the future of travel. Expedia Group’s ecosystem includes three flagship consumer brands – Expedia®, Hotels.com®, and...

Expedia Group's Top Stability & Growth Strengths
Strong Revenue Growth: Recent quarters delivered double-digit year-over-year gains in revenue (Q1 +15%, Q2 +14%), and management raised the 2026 outlook to about 9–10% revenue growth after results exceeded guidance. This builds on 2025’s double-digit Q4 growth and an 8% full‑year revenue increase.
Diversified Revenue Streams: Strength across consumer brands, sustained expansion in B2B, and contributions from the EG Advertising business are cited as key growth engines. This spread across channels and monetization types supports continued momentum.
Strategic Partnerships: Ongoing expansion in B2B partnerships and the unification of B2B and supply leadership aim to tighten execution, with new distribution wins such as Allegiant and a pending CarTrawler acquisition reinforcing partner-led growth. These moves broaden reach and deepen platform integration.
We contribute to human progress by empowering people to express themselves, live in the moment, learn about the world, and have fun together.

Snap Inc.'s Top Stability & Growth Strengths
Strong Revenue Growth: Revenue accelerated to about $1.60B in Q2 2026, up 19% year over year, following 12% growth in Q1 2026 and an 11% increase for full-year 2025. Rising ARPU alongside expanding DAU/MAU supported this top-line momentum.
Healthy Cash Flow: Q2 2026 free cash flow reached roughly $121M and operating cash flow improved to about $176M, both sharply higher year over year. These gains indicate improved operating efficiency even as GAAP net income remains negative.
Diversified Revenue Streams: “Other revenue” driven by subscriptions like Snapchat+ grew ~85% year over year in Q2 2026 (after ~87% in Q1), and Snapchat+ surpassed 25M subscribers by mid‑2026. This diversification is complementing ad recovery and helping sustain growth.
.png)
Collectors has multiple business lines that grade, authenticate, and sell millions of high-value, record-setting collectibles. We're the leader in third-party authentication and grading services for high-value collectibles including trading cards (Professional Sports Authenticator and Card Ladder), coins (Professional Coin Grading Services), video games (Wata), event tickets, autographs, and memorabilia, and with your help we can continue to grow rapidly. Our...

Collectors's Top Stability & Growth Strengths
Market Expansion: PSA announced two new U.S. grading hubs (Plano, TX and Boca Raton, FL) and its first full‑scale European facility in Frankfurt targeted for summer 2026. Feedback suggests these moves are aimed at increasing throughput and serving growing international demand.
Strategic Partnerships: In May 2024, Collectors and eBay completed transactions to integrate vaulting, grading, and selling—PSA acquired the eBay Vault and the firms entered a commercial agreement. Feedback suggests this creates a more end‑to‑end hobby stack that can drive submissions and liquidity.
Investor Backing & Capital Strength: Sports Business Journal reported a planned $200M investment to expand operations and hire around 1,000 roles through 2026, alongside earlier financing of $100M at a multibillion valuation. These commitments indicate ample capital to scale facilities, technology, and headcount.



