Top IT Companies in Toronto (509)
.png)
Expedia Group, Inc. is the global travel marketplace with one purpose: to help travelers explore the world, one journey at a time. Expedia Group™ connects travelers, partners, and advertisers through its trusted brands, leading technology, and rich first-party data, delivering predictive, personalized experiences that shape the future of travel. Expedia Group’s ecosystem includes three flagship consumer brands – Expedia®, Hotels.com®, and...

Expedia Group's Top Stability & Growth Strengths
Strong Revenue Growth: Recent quarters delivered double-digit year-over-year gains in revenue (Q1 +15%, Q2 +14%), and management raised the 2026 outlook to about 9–10% revenue growth after results exceeded guidance. This builds on 2025’s double-digit Q4 growth and an 8% full‑year revenue increase.
Diversified Revenue Streams: Strength across consumer brands, sustained expansion in B2B, and contributions from the EG Advertising business are cited as key growth engines. This spread across channels and monetization types supports continued momentum.
Strategic Partnerships: Ongoing expansion in B2B partnerships and the unification of B2B and supply leadership aim to tighten execution, with new distribution wins such as Allegiant and a pending CarTrawler acquisition reinforcing partner-led growth. These moves broaden reach and deepen platform integration.
Toast is the all-in-one platform built for restaurants of all sizes. Toast provides a single platform of software as a service (SaaS) products and financial technology solutions that give restaurants everything they need to run their business, including point of sale, payments, supplier management, digital ordering and delivery, marketing and loyalty, and team management. By serving as the restaurant operating...
Toast's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue rose about 23% year over year in Q2 2026 and 24% for full-year 2025, with ARR up 25% and GPV up 22% reinforcing a scaling top line. Guidance for 2026 recurring gross profit growth of roughly 23–25% further underpins momentum.
Profitability: Operating income and EPS roughly doubled year over year in Q2 2026 (operating income $152M vs. $80M; diluted EPS $0.26 vs. $0.13). Management also highlighted rising adjusted EBITDA and improved net income alongside recurring gross profit expansion.
Market Expansion: New offerings (e.g., Toast Drive‑Thru) and enterprise wins/expansions (e.g., Best Western, TGI Fridays UK, multi‑unit brands like Caribou Coffee and Potbelly) support broader adoption. The footprint reached about 180,000 total locations as of June 30, 2026, up roughly 22% year over year.
PagerDuty, Inc. (NYSE:PD) is a global leader in digital operations management, enabling customers to achieve operational efficiency at scale with the PagerDuty Operations Cloud. The PagerDuty Operations Cloud combines AIOps, Automation, Customer Service Operations and Incident Management with a powerful generative AI assistant to create a flexible, resilient and scalable platform to increase innovation velocity, grow revenue, reduce cost, and...

PagerDuty's Top Stability & Growth Strengths
Profitability: FY2026 marked the first full year of GAAP profitability, and Q1 FY2027 delivered a fourth consecutive GAAP‑profitable quarter. Profit guidance and expanding non‑GAAP operating margins indicate continued bottom‑line strength.
Healthy Cash Flow: Free cash flow was $102.7M in FY2026 and $41.2M in Q1 FY2027. Cash and investments of $444M and a $100M share repurchase authorization underscore liquidity to invest while returning capital.
Future-Ready Strategy: Management emphasizes AI‑first Operations Cloud offerings and a new usage‑based package aimed at re‑accelerating growth. Product and packaging moves are positioned to drive longer‑term expansion and retention.

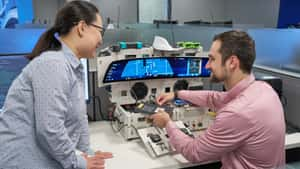
At General Motors, our vision is to create a world with Zero Crashes, Zero Emissions, and Zero Congestion. We wholeheartedly embrace the responsibility to lead the change that will make our world better, safer, and more equitable for all. Our industry and company are undergoing a once-in-a-lifetime technological transformation, which is reshaping our approach to technology and innovation. We are expanding...
General Motors's Top Stability & Growth Strengths
Profitability: Profit metrics and margins are rising in 2026, with Q2 EBIT‑adjusted up ~30% to $3.94B and the margin improving to 8.2%, alongside a first‑half margin of 8.9%. Management also raised full‑year 2026 profit guidance to $14–$16B, reflecting stronger earnings power driven by mix, pricing, and cost discipline.
Healthy Cash Flow: Adjusted automotive free cash flow grew sharply (up 78% in Q2 and 73% year to date), and the company reinforced confidence by declaring a $0.18 quarterly dividend and authorizing a $6B buyback. These capital returns accompany higher full‑year free‑cash‑flow guidance of $9.5–$11.5B.
Diversified Revenue Streams: Software‑enabled services and subscriptions are contributing more meaningfully, with roughly 620,000 subscribers, $5.4B of deferred revenue at 2025 year‑end, and OnStar revenue up ~20% year over year in Q2 2026. The company indicates software revenue is on track to exceed $3B in 2026.
HiBob helps modern, mid-size businesses transform the way they manage people, giving HR and managers all they need to connect, engage, develop, and retain top talent. Since 2015, we’ve achieved consecutive triple-digit year-over-year growth, all backed by our amazing team of Bobbers from across the globe, making us the choice HRIS of over 4000 midsize and multinational companies. Our HR platform...
HiBob's Top Stability & Growth Strengths
Strong Revenue Growth: ARR is characterized as moving from roughly $197M in 2025 to $250M+ by 2026, alongside customer and user counts rising from ~4,400/1.1M to 5,000+/1.3M through 2025. These directional milestones point to ongoing top-line expansion even without audited financials.
Market Expansion: The suite broadened with the Mosaic FP&A acquisition and the launch of Bob Finance in late 2025, complementing prior payroll moves and a Toronto office opening to deepen North American reach. These steps expand cross-sell/upsell potential and support penetration beyond core HR.
Investor Backing & Capital Strength: Successive $150M raises in 2021, 2022, and 2023 and a valuation reported near $2.7B by 2023 leave the company well capitalized (≈$574M total). This capital base enables continued product investment and go-to-market scale.
TransUnion is a global information and insights company that makes trust possible by ensuring that each consumer is reliably and safely represented in the marketplace. We do this by having an accurate and comprehensive picture of each person. This picture is grounded in our legacy as a credit reporting agency which enables us to tap into both credit and public record...
TransUnion's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is advancing at a double‑digit pace in early 2026, with successive quarters outperforming internal targets and full‑year guidance raised. Momentum is driven by U.S. Financial Services and improving International trends.
Profitability: Earnings are expanding, with adjusted EBITDA and adjusted EPS up year over year and full‑year guidance implying further gains. Absolute EBITDA improved even as the company invested and integrated recent acquisitions.
Market Expansion: Reach is widening through improved performance in Canada, the U.K., and India, alongside completed acquisitions in Mexico and a mobile division that extend capabilities. These moves contributed to stronger reported results and a higher outlook.
WorkWhile is an AI-powered next generation labor platform that helps businesses in light industrial, hospitality, and events achieve over 90% fill rates and reduce no-shows through AI and predictive machine learning. We ensure seamless shift execution with trained, on-demand workers supported by on-site leads, real-time performance monitoring, and a robust accountability system. Our worker-first model boosts retention through benefits like...

WorkWhile's Top Stability & Growth Strengths
Strong Revenue Growth: Independent recognition via the 2025 Inc. 5000 (reflecting strong multi‑year expansion) alongside company‑reported rapid recent growth indicates sustained topline momentum into 2026.
Investor Backing & Capital Strength: A $23M Series B closed in June 2025, with mainstream coverage noting baseline platform scale at that time, underscores access to capital to fund product and go‑to‑market expansion.
Strategic Partnerships: A 2026 Dayforce alliance reportedly brought 100+ Flex Work customers live within weeks, and collaborations around financial tools and healthcare signal broadened enterprise distribution and ecosystem reach.
As the AI platform for business transformation, we're putting AI to work across organizations — freeing people for work that matters. Making old tech work with new tech. Reaching across departments, from the front office to the back office and every office in between. Our ambition? To become the AI defining enterprise software company of the 21st century (or "AI...
ServiceNow's Top Stability & Growth Strengths
Strong Revenue Growth: Subscription revenue reached $3.877B in Q2 2026, growing strongly year over year, with total revenue also advancing. The company raised its full-year 2026 subscription outlook to $15.76–$15.78B and guided continued double-digit growth into Q3.
Product Line Growth: “ServiceNow AI” surpassed $1B in ACV in Q2 2026, acting as a catalyst for deal activity and upsell. Newer AI capabilities layered onto core workflows are described as adding incremental momentum.
Resilient & Sustainable Growth: Current and total RPO climbed to $13.20B and $29.0B, respectively, indicating strong contracted demand ahead. The number of customers above $5M in ACV increased meaningfully, supporting durable multi‑year expansion.
Qualtrics is trusted by thousands of the world’s best organizations to power exceptional customer and employee experiences that build deep human connections, increase customer loyalty, boost employee engagement, and drive business success. Our advanced AI and specialized Experience Agents™ allow businesses and governments to proactively interact with customers and employees in personalized ways across every channel and touchpoint, respond in-the-moment...
Qualtrics's Top Stability & Growth Strengths
Strong Market Position & Advantage: Independent analysts continue to place Qualtrics at the front of its market, with Gartner naming it a Leader in the Magic Quadrant for Voice of the Customer Platforms and positioning it highest on Ability to Execute and furthest on Completeness of Vision. This standing typically aligns with robust enterprise demand and supports commercial momentum.
Market Expansion: The company closed a $6.75 billion acquisition of Press Ganey Forsta on May 18, 2026, materially expanding its healthcare experience footprint and enlarging its data assets. Such scope increases are noted as common precursors to revenue growth and broader vertical penetration.
Innovation-Driven Growth: Qualtrics highlights rapidly expanding AI capabilities and analysis of billions of interactions annually, with usage of AI features surging and adoption widespread among large enterprise accounts. This product momentum supports upsell and cross‑sell into the installed base.

Citadel Securities is a technology-driven, next-generation global market maker. We provide institutional and retail investors with world-class liquidity, competitive pricing and seamless front-to-back execution in a broad array of financial products. Our teams of engineers, traders and researchers harness leading-edge quantitative research and the accelerating power of compute, machine learning and AI to power our analytics and tackle the market’s...
Citadel Securities's Top Stability & Growth Strengths
Strong Revenue Growth: Recent disclosures point to record annual and early‑year trading results in 2025–2026, signaling sustained top‑line momentum. Company communications also highlight elevated platform activity in options and expanded client analytics, reinforcing growth.
Market Expansion: A new Amsterdam office and recent build‑outs in Tokyo and Sydney indicate active geographic scaling across Europe and Asia‑Pacific. Increased global hiring across trading, engineering, and research supports deeper regional coverage and client reach.
Strong Market Position & Advantage: Materials emphasize a leading role in U.S. equities and retail order flow alongside prominent standings in U.S. Treasuries and investment‑grade credit. Record retail options activity and investment in high‑touch coverage integrated with electronic scale suggest durable competitive advantages.
iManage is dedicated to Making Knowledge Work. Over one million professionals across 65+ countries rely on our intelligent, cloud-enabled, secure knowledge work platform to uncover & activate the knowledge that exists inside their business content and communications. We are continuously innovating to solve the most complex professional challenges & enable better business outcomes. Our work is not always easy but it...

iManage's Top Stability & Growth Strengths
Strong Revenue Growth: ARR is reported up 42% year over year in 2024 with a further 28% uplift cited year‑to‑date in late 2025 and continued growth into 2026. Cloud ARR also rose strongly across 2023–2026, reinforcing top‑line momentum.
Market Expansion: New‑customer additions of 305 in 2024, 340 in 2025, and 90 early in 2026, alongside cloud adoption reaching 78% of the base, point to a widening footprint. Additional Azure regions (e.g., Switzerland) and thousands of organizations served further indicate expanded reach.
Innovation-Driven Growth: New AI‑powered offerings such as Ask iManage, iManage AI Enrichment, and Mailbox Assistant, plus secure MCP integrations, signal product‑led expansion. An expanded partnership with Thomson Reuters to deliver governed AI‑powered workflows underscores focus on AI‑enabled growth.
Founded in 2001, Vivid Seats is a leading online ticket marketplace committed to becoming the ultimate partner for connecting fans to the live events, artists, and teams they love. Based on the belief that “Life Happens Live”, the Chicago-based company provides exceptional value by providing one of the widest selections of events and tickets in North America and an industry...
Vivid Seats's Top Stability & Growth Strengths
Cost & Operational Efficiency: Cost-reduction efforts and a simplified corporate structure carried into 2026, with adjusted EBITDA improving sequentially from late 2025 into Q1 and Q2 2026. Management frames these actions as an operational reset supporting stabilization.
Future-Ready Strategy: App engagement is being emphasized, with rising app GOV share and stronger user engagement alongside a focus on private‑label partnerships. These initiatives are positioned to lessen dependence on paid acquisition and support a return to growth.
Market Expansion: Acquisitions such as Wavedash in Japan and Vegas.com, plus new partnerships with major sports teams, broaden geographic and category reach. The company also raised its 2026 outlook after Q2, aided by event-driven demand.
Together, we turn ambition into action. For more than three decades, Citadel has captured undiscovered market opportunities in markets around the world by empowering extraordinary people to pursue their best and boldest ideas. We strive to identify the highest and best uses of capital to generate superior long-term returns for the world’s preeminent public and private institutions.
Citadel's Top Stability & Growth Strengths
Profitability: All‑time profit leadership and continued gains in 2024–2025 underpin sustained investor demand and fee generation. Returning roughly $5 billion of 2025 profits while maintaining about $66–$67 billion in AUM highlights durable earnings and disciplined sizing.
Market Expansion: The Miami headquarters build, additional 2026 real‑estate purchases, and a planned Dubai office point to an expanding physical footprint and long‑dated strategic commitments. Acquisitions in power and energy trading (e.g., FlexPower and Paloma Natural Gas) extend reach into global commodities markets.
Strong Hiring & Retention: Ongoing large‑scale recruiting, including new cohorts for the Citadel Associate Program and other early‑career pipelines, signals sustained investment in talent to support platform growth.
Stablecorp is a leading Canadian fintech firm building digital money infrastructure to support the global payments space. Through its digital money APIs, Stablecorp has created a suite of embedded digital money solutions that power a variety of financial use cases. For more information, visit https://www.stablecorp.ca

Happiest Minds Technologies Limited (NSE: HAPPSTMNDS), a Mindful IT Company, enables digital transformation for enterprises and technology providers by delivering seamless customer experiences, business efficiency and actionable insights. We do this by leveraging a spectrum of disruptive technologies such as: artificial intelligence, blockchain, cloud, digital process automation, internet of things, robotics/drones, security, virtual/augmented reality, etc. Positioned as ‘Born Digital ....

Box (NYSE:BOX) is the leading Content Cloud, a single platform that empowers organizations to manage the entire content lifecycle, work securely from anywhere, and integrate across best of breed apps. Founded in 2005, Box simplifies work for leading global organizations, including AstraZeneca, JLL, and Nationwide. Box is headquartered in Redwood City, CA, with offices across the United States, Europe, and...

Box's Top Stability & Growth Strengths
Strong Market Position & Advantage: Recognition as a Leader by Gartner (Document Management 2024/2026), IDC (Intelligent Content Services 2024), and Forrester (Content Platforms 2025), alongside adoption by 97,000+ companies and 68% of the Fortune 500, highlights durable competitive standing. Billion‑dollar revenue scale reinforces enterprise relevance across modern document and content services categories.
Resilient & Sustainable Growth: FY2026 revenue of about $1.18B rose roughly 8%, Q1 FY2027 grew 11% year over year, and guidance for FY2027 implies about 8–9% growth. Double‑digit RPO growth in Q4 FY26 (+17%) and Q1 FY27 (+12%) provides visibility into future revenue.
Cost & Operational Efficiency: Non‑GAAP operating margin reached 30.6% in Q4 FY26 and 27.7% in Q1 FY27, with FY27 guidance near 28%, indicating operating leverage. Ongoing share repurchases alongside expanding margins suggest disciplined cost control and capital deployment.
Relentless protection. Resilient world. Mimecast (NASDAQ: MIME) was born in 2003 with a focus on delivering relentless protection. Each day, we take on cyber disruption for our tens of thousands of customers around the globe; always putting them first, and never giving up on tackling their biggest security challenges together. We are the company that built an intentional and scalable design...
Mimecast's Top Stability & Growth Strengths
Strong Market Position & Advantage: Mimecast is positioned as a leader in email security platforms, supported by repeated Gartner Magic Quadrant Leader placements and a large global customer footprint. The scale of threat processing and breadth of security, archiving, and continuity capabilities reinforce competitive advantage in its core market.
Strong Revenue Growth: Revenue is described as increasing year-over-year through fiscal 2025, with references to record new and expansion revenue gains. Projected net income growth into 2026 is presented as an additional indicator of strengthening financial momentum.
Product Line Growth: The platform is expanding beyond email security into human risk management, insider risk, and collaboration security via acquisitions such as Elevate Security, Code42, and Aware. Ongoing launches like Cloud Integrated Email Security and expanded modules (e.g., DMARC tools, add-ons for archiving/continuity) indicate continued portfolio broadening.

We help companies modernize business operations, adopt intelligent automation, deliver real-time performance insights and connect the enterprise – accelerating the impact of digital transformation. Founded in 1987 and recognized as a trusted advisor, HSO is one of the world’s top business solution and implementation partners, large enough to serve, small enough to care. Our Global Footprint and Delivery Capabilities HSO is 100%...

Q&C is the largest independent full-service consultant and importer for Health Canada, US FDA and internationally regulated drugs, APIs, natural health products and medical devices. We bring over 25 years of experience to our clients, providing expert consulting on regulatory and compliance matters, including industry best practices, assistance passing inspections and audits, and authoritative guidance for drug importation into Canada....

Wisevu is a professional digital marketing & consulting agency specializing in developing and implementing custom online business strategies for Canadian businesses with local and international reach. Our 3 core services include: 1. Web Design & Development 2. SEO 3. Facebook Marketing Wisevu Mission Our mission can not be defined without first defining "Wisdom". “Wisdom is the ability to perform the action(s) with the highest degree of...